
An article on mental health drew a distinction that stayed with me: a higher statistical likelihood of developing a condition is not the same as an inevitable outcome.
Certain circumstances or experiences may substantially increase the risk of a mental health condition. That does not mean everyone who goes through them will develop it.
The distinction matters far beyond that context. It has implications for how we plan our lives and, in particular, how we make business and financial decisions.
Sometimes we quietly turn a high probability into a guarantee, then build our decisions around it without noticing.
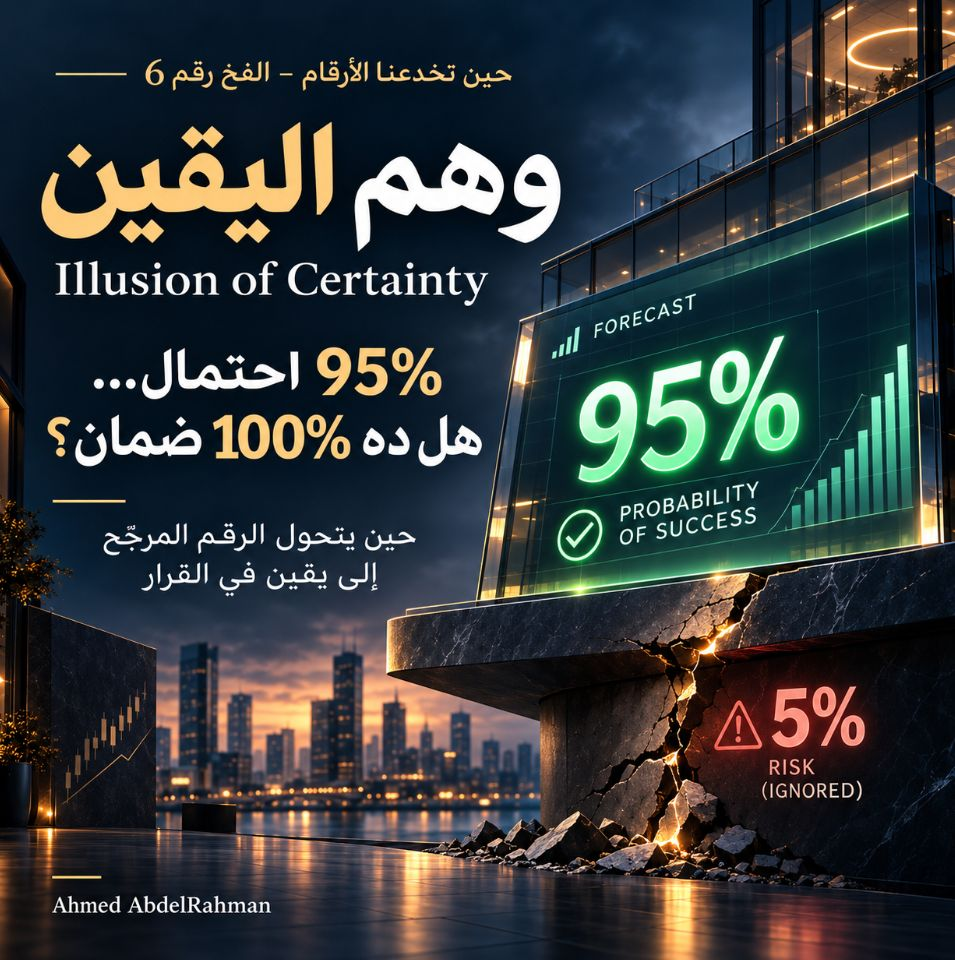
A 95% probability is not a guarantee
Imagine your company expects a substantial customer payment on Thursday. The collections team puts the probability of receiving it on time at 95%.
That is reassuring, and the estimate may be backed by excellent data and analysis. But does it justify committing to payments due on Friday, relying entirely on that receipt with no fallback?
This is the decision trap I call the illusion of certainty: a statistically likely outcome gradually becomes an established fact in our thinking.
A 95% probability means the outcome is highly likely, assuming the estimate is sound. It does not promise that it will happen this time. Nor is the remaining 5% simply a rounding error we can ignore.
The question is not only, “How likely is the risk?” It is also, “What happens if it materialises, and can we absorb the consequences?”
If a two-day delay merely postpones a non-essential expense, the impact may be modest.
If the same delay leaves the company unable to meet obligations, breaches financing terms, or disrupts essential operations, it calls for a different response, even with only a 5% chance of happening.
The average may not be a possible outcome
The problem is not always excessive confidence in probabilities. Sometimes it is how we use them in planning.
Consider a budgeting example. A company is bidding for a contract worth EGP 1 million in revenue, with an estimated 50% chance of winning.
Should the budget include EGP 500,000 of revenue, calculated by multiplying the contract value by the probability of winning? The calculation is mathematically correct: it is the expected value. But how useful is it for this particular decision?
The company will not win half the contract. It will either win it or lose it.
If it loses, the budget shows an adverse revenue variance of EGP 500,000. If it wins and earns the full million, it shows a favourable variance of the same amount.
Neither result necessarily tells us that planning was poor or performance was strong. Both were possible from the outset.
Here, the probability-weighted average is not even an outcome that can occur. Using it as the revenue budget for a single bid can make variance analysis misleading if we treat it as a performance benchmark.
That does not make probability-weighted planning wrong. Across a large portfolio of reasonably independent bids or contracts, expected value can be a highly useful way to estimate aggregate revenue.
For a single, binary outcome, however, it may be more useful to show both scenarios and their implications than to reduce them to an average that neither scenario will produce.
An expected value is not necessarily an outcome you can expect to observe.
A default probability is not a verdict on a borrower
The same reasoning applies to lending portfolios. A model assigning a borrower a 2% probability of default does not establish that the borrower will repay, or that they will default.
It is a risk estimate, not a verdict on that borrower’s future. At portfolio level, such estimates can inform pricing, risk management, and expected credit losses. They still offer no guarantee about any individual case.
How much confidence should we place in the estimate?
There is another equally important question: how reliable is the probability estimate itself? Is the model based on enough data? Has it been tested? Do the conditions behind the historical data still hold?
A model reporting a 95% chance of success is one thing. Having good reason to trust that 95% estimate is another.
That creates an additional trap: confidence in the number can quietly become overconfidence in the assumptions behind it.
Can we live with the decision if the forecast is wrong?
This is not an argument for preparing for the worst in every decision or tying up company resources against every conceivable risk. That would be poor judgment in its own right.
Good management balances the likelihood of a risk, the severity of its impact, the cost of preparing for it, and the organisation’s capacity to absorb the consequences.
That makes one question especially valuable when reviewing a financial plan or investment decision: if the most likely scenario does not happen, can we still live with the decision?
Forecasts being wrong is not the problem; uncertainty is part of dealing with the future. The problem is building plans as though error were impossible, or treating statistical averages as guaranteed outcomes.
High probability does not mean certainty. A good decision is not simply one that works when the forecast is right. It is one whose consequences we understand when the forecast is wrong.
Fallacies, biases, and decision traps finance professionals may face.